India’s Unified Payments Interface has become one of the most consequential pieces of digital infrastructure created anywhere in the world. What began in 2016 as an interoperable payments architecture has evolved into the backbone of India’s retail digital economy, connecting hundreds of banks, payment applications, merchants, consumers and public institutions through an open, real-time payment rail.
The scale of this transformation is extraordinary. UPI processed more than 24,161 crore transactions during FY 2025-26, with transaction value of approximately ₹314 lakh crore. The number of banks live on UPI increased from 44 in its early years to more than 700. In August 2026 alone, NPCI data recorded approximately 24.51 billion transactions worth ₹29.82 lakh crore. UPI now accounts for roughly 84-85% of India’s digital payment volume and around 49% of global real-time payment transaction volume, according to government and international-industry data.
This success, however, creates a paradox. The larger UPI becomes, the greater the economic value it creates, but also the larger the underlying infrastructure that must be continuously operated, upgraded and protected. Servers, network capacity, fraud monitoring, cybersecurity, authentication, dispute resolution, settlement infrastructure, redundancy, technical support, application programming interfaces, compliance systems and continuous product development all require investment.
The question therefore is no longer simply whether UPI should be free.
The more important question is:
Who should finance the infrastructure that makes nearly 800 million UPI transactions possible every day?
The new MDR framework announced for implementation from 15 October 2026 represents an important change in the economics of UPI. Under the framework, specified merchant transactions above ₹2,000 will attract an MDR of 0.4%, capped at ₹300 per transaction. Person-to-person transactions remain free, payments to merchants up to ₹2,000 remain protected, and specified small merchants continue to receive exemptions. The government has stated that approximately 96% of P2M transactions will remain unaffected.
This is therefore not simply a story about introducing a fee. It is the beginning of a debate about how India should finance, govern and continuously upgrade a piece of digital public infrastructure that has become systemically important to the economy.
From Payment Innovation to National Digital Infrastructure
When UPI was launched in 2016, India was solving a specific problem: how to make bank-to-bank digital payments interoperable, simple and instantaneous. Ten years later, the nature of the problem has changed.
UPI is no longer merely a payment product. It is an economic infrastructure layer. It enables small retail purchases, e-commerce, bill payments, subscriptions, transportation payments, education payments, insurance payments, capital-market transactions and person-to-person transfers. It has also become an important component of India’s financial inclusion architecture.
Government data shows the extraordinary trajectory. Annual UPI transaction volume rose from only 1.78 crore transactions in FY 2016-17 to more than 24,162 crore in FY 2025-26, an almost 13,000-fold increase. Annual transaction value increased from approximately ₹0.07 lakh crore to around ₹314 lakh crore.
This means that UPI is now processing an economic flow comparable to the size of India’s annual GDP multiple times over. August 2026 illustrates the new scale particularly well. NPCI recorded approximately 24,508.96 million transactions, equivalent to about 2,451 crore transactions, with a value of approximately ₹29.82 lakh crore.
At this scale, the distinction between a “free payment service” and “public digital infrastructure” becomes important. Roads may be free at the point of use. Electricity grids may not charge every citizen separately for every infrastructure component. Public internet infrastructure may be subsidised. But the underlying infrastructure still has operating and capital costs.
Digital infrastructure is no different.
The Economics Behind a “Free” UPI Transaction
The word “free” can be misleading. A consumer making a ₹500 UPI payment may pay nothing directly, but that does not mean the transaction costs nothing to the system.
Behind that payment are multiple layers:
- bank infrastructure;
- payment service providers;
- NPCI infrastructure;
- acquiring and issuing banks;
- authentication and security systems;
- cloud and data-centre capacity;
- telecommunications networks;
- fraud detection systems;
- customer support;
- dispute management;
- regulatory compliance;
- transaction monitoring;
- settlement and reconciliation;
- software development;
- cybersecurity;
- system redundancy and disaster recovery.
The Reserve Bank of India has previously highlighted the economic tension in digital payment pricing: excessively high charges can discourage adoption, while charges that are too low may become non-remunerative and discourage investment in payment infrastructure.
That observation is increasingly relevant to UPI. A payment ecosystem processing hundreds of millions of transactions every day cannot be managed as if its infrastructure requirements were static. The system must continuously increase capacity while simultaneously reducing downtime, detecting fraud faster, improving authentication, supporting new devices and payment modes, and integrating new participants.
Consequently, the economic model of UPI has to answer a basic infrastructure question:
How does a high-volume, low-cost payment system generate sufficient resources for continuous reinvestment?
The ₹20,000-Crore Question
Industry estimates cited in the current UPI pricing debate put the annual cost of operating the broader UPI ecosystem at approximately ₹20,000 crore. That number should be treated carefully. It is not equivalent to an officially audited statement that NPCI itself spends ₹20,000 crore every year. Rather, it represents an estimate of the broader ecosystem cost associated with maintaining the infrastructure, technology, security, processing and support required for UPI. At ₹20,000 crore a year, the arithmetic is striking.
The figure translates into approximately: ₹1,667 crore per month
or approximately: ₹54.8 crore per day
or approximately: ₹2.28 crore per hour.
These numbers provide a useful way of understanding the scale of the sustainability challenge. The infrastructure supporting UPI is operating continuously. It does not close at night. It cannot simply defer maintenance until the next financial year. Fraud monitoring cannot be switched off during weekends. Cybersecurity teams cannot work only when transaction volumes are low.
The system has to operate at national scale, around the clock. That makes sustainability a structural issue rather than a temporary accounting problem.
From Zero MDR to Sustainable MDR
India’s zero-MDR policy played an important role in UPI’s rapid adoption. The Government of India has repeatedly supported low-value digital transactions through incentive programmes. In FY 2024-25, the Union Cabinet approved a ₹1,500-crore incentive scheme for low-value BHIM-UPI P2M transactions, particularly supporting small merchants.
The logic was straightforward: reduce the economic barrier to digital adoption and accelerate India’s transition toward digital payments.
That strategy worked. But success changes the policy problem. When UPI was processing relatively small volumes, the question was how to achieve adoption. When UPI processes approximately 24.5 billion transactions in a month, the question becomes how to sustain and upgrade the system without undermining the adoption gains of the previous decade. The October 2026 framework attempts to separate these two objectives. It does not introduce a universal UPI charge. Instead, it creates a differentiated structure in which:
P2P remains free.
Small-value merchant payments remain protected.
Eligible higher-value merchant payments contribute to the economics of the system.
Small merchants receive protection through exemptions.
This is significant because it attempts to preserve UPI’s original inclusion objective while introducing greater financial sustainability at the higher-value end of the ecosystem.
What Exactly Changes From 15 October 2026?
The new framework is important precisely because it is more targeted than a blanket payment fee. For specified P2M transactions above ₹2,000, the standard MDR is 0.4%, with a maximum charge of ₹300 per transaction.
The ₹300 cap becomes relevant at ₹75,000 because: 0.4% × ₹75,000 = ₹300.
Therefore, for a transaction above ₹75,000, the MDR does not continue increasing proportionately. Several categories have differentiated treatment, including specified essential and public-service-linked transactions, where a flat charge of ₹5 applies under the announced framework. Capital-market transactions also receive a differentiated MDR structure.
Most importantly, the government has clarified that the MDR is not a tax collected by the government. It is an ecosystem charge distributed among participants such as banks and payment application providers.
The policy architecture therefore attempts to establish a market-based source of revenue without converting UPI into a direct consumer-facing fee system.
The 96% Question: Why the Threshold Matters
One of the most important facts in the current debate is that the government estimates approximately 96% of P2M transactions will remain unaffected. This is critical. UPI has become popular precisely because it works for ₹20, ₹50, ₹100, ₹250 and ₹500 payments. If the objective were simply revenue maximisation, a universal MDR would be easier to design.
But a universal charge could have disproportionately affected:
- street vendors;
- small retailers;
- kirana stores;
- domestic service providers;
- small restaurants;
- micro-enterprises;
- rural merchants;
- low-income consumers.
The current design attempts to avoid that problem by protecting small-ticket transactions and qualifying small merchants. Government data also shows that UPI has a very strong small-value character. The FY 2025-26 data indicates that a very large proportion of P2M transactions are below ₹500.
This creates an important policy principle:
The financing burden for national digital infrastructure should not fall disproportionately on the smallest transactions.
The 2026 framework broadly moves in that direction.
The Real Economic Debate: Who Should Pay?
There are four possible broad financing models for digital payment infrastructure.
Model 1: Consumers pay: Under this model, users pay a transaction fee. For UPI, this would be politically and economically disruptive because its success is partly built on frictionless consumer adoption. It could also discourage digital payments in price-sensitive segments.
Model 2: Merchants pay: This is closer to the traditional card-payment model. The merchant pays an MDR because the payment system provides a commercial service: instant settlement, lower cash handling requirements, digital records, customer convenience and potentially greater transaction efficiency.
The October 2026 framework follows this broad principle for specified transactions.
Model 3: Government pays: Government subsidies can support strategic digital infrastructure. India has already used this mechanism. The ₹1,500-crore incentive scheme for FY 2024-25 is an example. Government support can be justified when the infrastructure produces wider public benefits such as financial inclusion, formalisation and reduced dependence on cash.
But permanent full financing by the government can create fiscal dependence.
Model 4: Ecosystem pays: The fourth model is an ecosystem-based approach in which banks, payment applications, merchants, aggregators and other beneficiaries contribute according to the value they receive.
The new MDR framework moves UPI closer to this model. This is potentially significant because it transforms UPI from a predominantly subsidy-supported infrastructure model toward a shared economic model.
Why Sustainability Is More Than Paying the Electricity Bill
The most important mistake would be to view MDR revenue merely as money for “running servers.” The strategic requirement is much larger. UPI is entering its second decade.
The first decade was primarily about: adoption + interoperability + scale.
The next decade will require: security + intelligence + resilience + internationalisation + innovation.
The revenue architecture should therefore support at least six areas.
Infrastructure expansion
UPI transaction volumes continue to grow. Capacity has to expand ahead of demand rather than after failures occur.
That means:
- additional processing capacity;
- data-centre resilience;
- network redundancy;
- disaster recovery;
- real-time monitoring;
- geographic redundancy;
- higher system availability.
At national scale, even a small deterioration in availability can affect millions of transactions.
Cybersecurity Should Be One of the Biggest Beneficiaries
The economics of UPI cannot be separated from cybersecurity. As digital payments grow, the incentive for fraudsters grows as well. RBI has repeatedly identified cybersecurity as a prerequisite for wider digital-payment adoption. Phishing, malware, ransomware, man-in-the-middle attacks, social engineering and other forms of cybercrime can undermine consumer confidence and financial stability.
The future UPI security architecture therefore needs continuous investment in:
- AI-driven fraud detection;
- behavioural analytics;
- anomaly detection;
- mule-account identification;
- real-time risk scoring;
- device intelligence;
- biometric and behavioural authentication;
- transaction graph analysis;
- automated fraud response;
- cyber threat intelligence;
- secure APIs;
- quantum-resistant cryptography research.
A sustainable UPI should not simply be able to process more transactions. It should be able to process more transactions safely. That distinction will become increasingly important as UPI expands internationally.
MDR Could Become a Source of India’s Digital Payments R&D Fund
This may be the most important policy opportunity in the entire debate. The objective should not be merely:
MDR → operating expenses.
It should become:
MDR → operations + security + innovation + research + future infrastructure.
India has created a globally significant payment architecture. The next challenge is to ensure that the intellectual property, technology capabilities and research ecosystem surrounding it remain globally competitive.
A portion of ecosystem revenue could therefore be institutionalised as a Digital Payments Research and Innovation Fund.
Such a fund could support research in:
- AI-based payment security;
- privacy-preserving payments;
- offline digital payments;
- low-connectivity payments;
- voice-based UPI;
- multilingual interfaces;
- accessibility technologies;
- programmable payments;
- CBDC-UPI interoperability;
- tokenisation;
- cross-border payment interoperability;
- digital identity;
- quantum-safe payment infrastructure;
- post-quantum cryptography;
- payment fraud intelligence;
- financial inclusion technologies;
- open payment APIs;
- payment infrastructure for feature phones.
This would change the policy narrative fundamentally.
Instead of asking: “Why should UPI no longer be completely free?”
India could ask: “How do we convert the economic value generated by UPI into the next generation of Indian payment technology?”
From UPI Infrastructure to a Global Payment Technology Mission
UPI is already moving beyond India’s borders. Government data indicates that UPI has become operational in multiple countries, while international organisations and industry reports have recognised India’s leadership in real-time payments. This creates another economic opportunity.
If UPI becomes part of India’s international digital infrastructure strategy, investment will be needed in:
- international interoperability;
- currency conversion infrastructure;
- cross-border settlement;
- fraud management across jurisdictions;
- international compliance;
- data governance;
- cybersecurity;
- dispute resolution;
- multilingual customer interfaces;
- sovereign digital-payment partnerships.
The economics of domestic UPI therefore have consequences for India’s international ambitions. A sustainable domestic payment rail can become the foundation for a much larger Indian digital-payment technology ecosystem.
UPI as a Strategic Digital Public Infrastructure
The global importance of UPI is not simply its transaction volume. Its deeper significance lies in its architecture. UPI demonstrates that digital public infrastructure can combine:
interoperability + competition + low cost + scale + public standards.
This is different from a closed private payment platform. The network is designed so that multiple banks and applications can participate. That architecture has generated enormous positive externalities. A merchant can receive payments from customers using different applications. A consumer can send money across banks. Businesses can integrate payments through APIs. New fintech companies can build products on top of the underlying rail.
This is a classic characteristic of infrastructure:
its economic value is larger than the revenue captured by the infrastructure provider itself.
That is why government participation and regulatory oversight remain important. But infrastructure also needs a sustainable financing model.
The International Comparison Is Important
India should also learn from other payment ecosystems. Card networks such as Visa and Mastercard historically operate with explicit interchange, assessment and merchant-service economics. China’s digital-payment ecosystem developed around major commercial platforms with multiple monetisation channels. Brazil’s Pix created a powerful instant-payment infrastructure under central-bank leadership, with an emphasis on interoperability and low-cost access. Europe has pursued instant-payment expansion while strengthening competition, consumer protection and interoperability.
India’s UPI model is different.
Its distinctive achievement has been to combine public digital infrastructure with private innovation at enormous scale. That makes the economic design particularly important. India does not need to copy card economics. Nor does it need to convert UPI into a conventional commercial platform.
Instead, it can develop a third model:
Sustainable Digital Public Infrastructure
where:
- basic access remains affordable;
- P2P remains free;
- small merchants are protected;
- commercial high-value transactions contribute;
- ecosystem participants receive economic incentives;
- cybersecurity receives dedicated investment;
- research receives predictable funding;
- infrastructure upgrades are financed continuously;
- competition remains open;
- consumers remain protected.
This could become a model for other countries building digital public infrastructure.
The ₹2,000 Threshold Could Create New Behaviour
Every threshold creates incentives. If transactions above ₹2,000 attract MDR while those below ₹2,000 do not, some merchants or consumers may attempt to restructure payments. For example, a ₹10,000 purchase could theoretically be divided into multiple transactions.
That creates a policy requirement for intelligent monitoring. The objective should not be to police ordinary consumer behaviour aggressively.
Instead, the system can use transaction analytics to identify suspicious patterns such as:
- repeated split payments;
- rapid sequential transactions;
- multiple transactions between the same accounts;
- artificial invoice fragmentation;
- coordinated merchant behaviour.
This is another reason why MDR revenue should support sophisticated payment intelligence. The future payment system must be capable not only of processing transactions but also of understanding transaction behaviour.
A Possible “UPI Sustainability Framework”
India could institutionalise a transparent framework around the new MDR model.
Pillar 1: Core Infrastructure Fund
A defined share of MDR revenue could finance:
- servers;
- network capacity;
- redundancy;
- disaster recovery;
- system upgrades.
Pillar 2: Cybersecurity Fund
A dedicated pool could support:
- fraud prevention;
- AI-based risk engines;
- cyber threat intelligence;
- security audits;
- national payment security research.
Pillar 3: Research & Innovation Fund
A portion could finance university-industry research into:
- AI;
- cryptography;
- privacy;
- quantum-safe systems;
- offline payments;
- multilingual interfaces;
- cross-border payments.
Pillar 4: Inclusion Fund
A dedicated component could support:
- rural merchants;
- feature-phone users;
- low-connectivity regions;
- accessibility;
- senior citizens;
- persons with disabilities;
- small enterprises.
Pillar 5: Internationalisation Fund
India could invest in:
- cross-border interoperability;
- international standards;
- sovereign payment partnerships;
- settlement technologies;
- global fraud management.
Pillar 6: Consumer Protection Fund
A proportion of ecosystem revenues could strengthen:
- dispute resolution;
- fraud compensation mechanisms;
- awareness programmes;
- grievance redressal;
- digital financial literacy.
Such a structure would make the economics of UPI more transparent and strategically aligned with national development.
The Next UPI Must Be More Than a QR Code
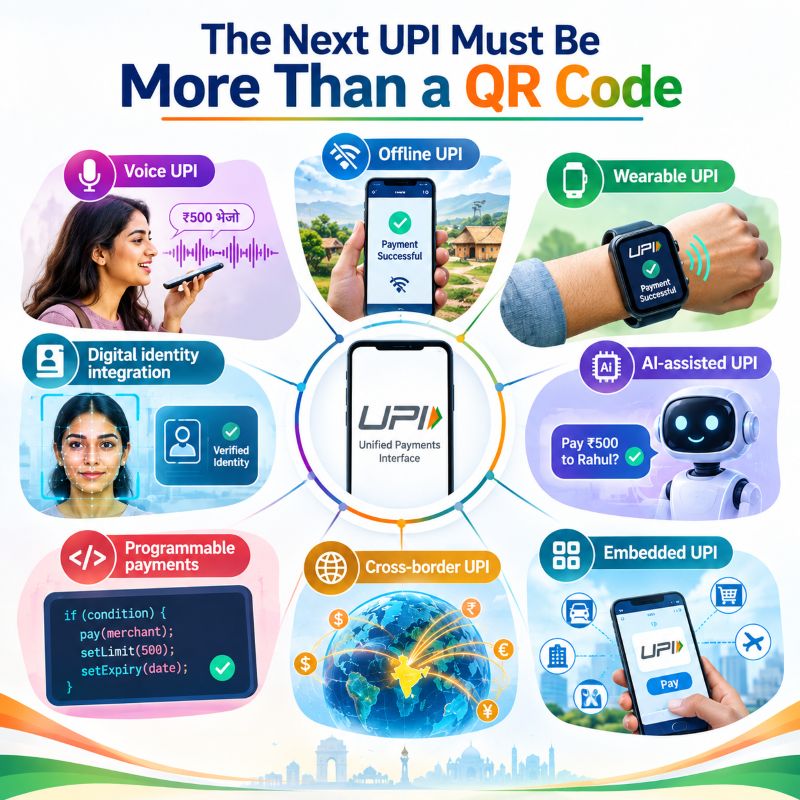
The first generation of UPI was largely associated with QR codes and smartphone-based payments. The next generation can be considerably broader. India is already exploring and deploying new payment interfaces such as NFC-based tap-and-pay mechanisms, while UPI 123PAY has expanded the potential for feature-phone users.
Future UPI could increasingly include: Voice UPI
Payments initiated through Indian-language voice commands. Offline UPI
Payments in areas with weak or intermittent connectivity. Wearable UPI
Payments through watches and other devices. AI-assisted UPI
Intelligent payment recommendations, fraud alerts and personalised financial interfaces. Embedded UPI
Payments integrated into transport, commerce, government and enterprise systems. Cross-border UPI
Real-time international payments using interoperable payment rails. Programmable payments
Payments linked to contractual, institutional or business rules. Digital identity integration
Stronger authentication without increasing friction. These innovations require R&D. And R&D requires funding.
The Case for a National Digital Payments Research Network
India should consider creating a National Digital Payments Research Network connecting:
- NPCI;
- RBI;
- IITs;
- IISc;
- IIMs;
- IIITs;
- central universities;
- fintech companies;
- cybersecurity institutions;
- banks;
- payment applications;
- telecom companies;
- global research organisations.
The network could publish an annual:
State of India’s Digital Payments Report
It could measure:
- transaction growth;
- cost of payments;
- merchant economics;
- fraud;
- cybersecurity;
- rural adoption;
- financial inclusion;
- innovation;
- internationalisation;
- payment infrastructure resilience;
- consumer protection.
This would make India’s payment-policy debate more evidence-based.
UPI’s Next Challenge Is Not Adoption. It Is Resilience.
For much of the last decade, India’s digital-payment policy could be summarised as: Get more people onto digital payments.
The next decade requires a different objective: Make the digital payment ecosystem resilient enough to support a $5-trillion-plus and eventually much larger economy.
At current volumes, even a one-hour disruption has enormous economic consequences. The infrastructure therefore needs the resilience standards associated with other critical national systems.
This includes:
- multi-region redundancy;
- cyber-resilience;
- disaster recovery;
- real-time system monitoring;
- stress testing;
- capacity planning;
- operational risk management;
- independent security testing;
- rapid incident response.
The cost of resilience should be viewed as an investment rather than an unnecessary overhead.
Why “Free” and “Affordable” Are Not the Same Thing
The public debate often presents two options: Free UPI versus Paid UPI. That is too simplistic.
There is a third possibility:
Affordable UPI with sustainable infrastructure economics.
The consumer does not necessarily have to pay. A ₹100 UPI payment can remain free to the consumer. A ₹500 payment can remain free. A person sending ₹50,000 to a family member can remain free under the P2P framework. But a large commercial transaction can contribute a small amount to the infrastructure that makes the transaction possible. That is not the same as abandoning free digital payments.
It is a move toward differentiated pricing based on use and economic capacity.
The Larger Lesson for Viksit Bharat
The UPI debate has significance well beyond payment charges. It raises a fundamental question for India’s development model:
How should Digital Public Infrastructure be financed once it reaches global scale?
India has successfully built several digital public infrastructure layers. Aadhaar created a digital identity foundation. UPI created an interoperable payment rail. FASTag transformed toll payments. DigiLocker created digital document infrastructure. ONDC is attempting to create open digital commerce infrastructure. The next stage of Viksit Bharat will require these platforms to become financially, technologically and institutionally sustainable.
The lesson is important:
Public infrastructure does not necessarily mean that every underlying service must be permanently free of economic cost.
Public interest should determine the architecture. Market mechanisms can determine part of the financing. Government support can address externalities and inclusion. Private participants can compete and innovate. The combination can create a sustainable digital ecosystem.
Five Principles for the Future UPI Economy
India’s next-generation UPI framework should be built around five principles.
1. Protect the citizen: P2P transactions and essential low-value digital payments should remain affordable and accessible.
2. Protect the small merchant: Micro and small businesses should not become unintended casualties of infrastructure financing.
3. Monetise commercial value: Large commercial transactions that derive significant economic benefit from instant digital infrastructure can contribute proportionately.
4. Reinvest in the ecosystem: Revenue should translate into better infrastructure, cybersecurity, innovation and customer support rather than merely becoming financial extraction.
5. Maintain transparency: The ecosystem should publish periodic information about how MDR revenue is distributed and what categories of infrastructure and innovation it supports.
Transparency will be essential for public trust.
From Free UPI to Sustainable UPI
India should not view the October 2026 MDR decision merely as the end of free UPI. That description misses the larger transformation. UPI itself is not becoming a conventional paid payment service. P2P transactions remain free. Small-value payments remain protected. Small merchants receive exemptions. The government estimates that approximately 96% of P2M transactions will remain unaffected.
What is changing is the economic architecture behind the system. For a decade, India prioritised adoption. The next decade must prioritise sustainability, resilience and innovation. A payment system processing more than 24 billion transactions a month cannot rely indefinitely on an economic model in which the majority of infrastructure costs are absorbed indirectly by banks, payment companies and government-supported mechanisms.
At the same time, India must avoid creating a fee structure that discourages digitalisation or disproportionately burdens small businesses. The appropriate objective is therefore neither “free at any cost” nor “monetise everything.”
It is:
Affordable access + sustainable infrastructure + continuous innovation.
The estimated ₹20,000-crore annual ecosystem cost should therefore be seen not merely as an expense. It represents the economic scale of maintaining one of the world’s most important digital payment infrastructures. The real opportunity is to convert a part of that economic value into a long-term national investment.
Imagine a UPI ecosystem in which every rupee generated from sustainable commercial transactions helps finance the next generation of:
cybersecurity, AI-based fraud prevention, quantum-safe cryptography, offline payments, rural connectivity, accessibility, cross-border payments, digital financial inclusion and payment technology research.
That would transform the debate.
The question would no longer be: “Why is UPI not free?”
It would become: “How do we ensure that India’s digital payment infrastructure remains world-class for the next 25 years?”
That is the more important question for a Viksit Bharat. India did not build UPI merely to make payments easier. It built UPI as a digital public infrastructure capable of changing how an economy functions. The first decade proved that India can build digital infrastructure at population scale.
The next decade must prove that India can finance it, secure it, continuously innovate it and take it to the world. The transition from zero-MDR to a carefully targeted MDR framework should therefore be judged not only by the revenue it generates, but by what India chooses to do with that revenue.
If the money is converted into stronger infrastructure, better cybersecurity, deeper inclusion and globally competitive payment research, MDR can become more than a transaction charge.
It can become an investment in India’s digital sovereignty and the technological foundations of Viksit Bharat 2047.
